Polymer vs. Metal 3D Printing: Choosing the Right Process for Production — October 2026
When the B-21 Raider entered low-rate initial production at Northrop Grumman's Palmdale facility, it carried with it an estimated 1,000-plus additively manufactured components — a figure that would have been considered science fiction during the B-2's development in the late 1980s. The additive manufacturing revolution did not arrive with a single proclamation; it accumulated through decades of materials science, process qualification, and hard-won regulatory acceptance. Today, the question defense and aerospace manufacturers must answer is not whether to print — it is what to print, in which material, and at what cost per qualified part.
The Process Gap Is Wider Than Most Procurement Teams Realize
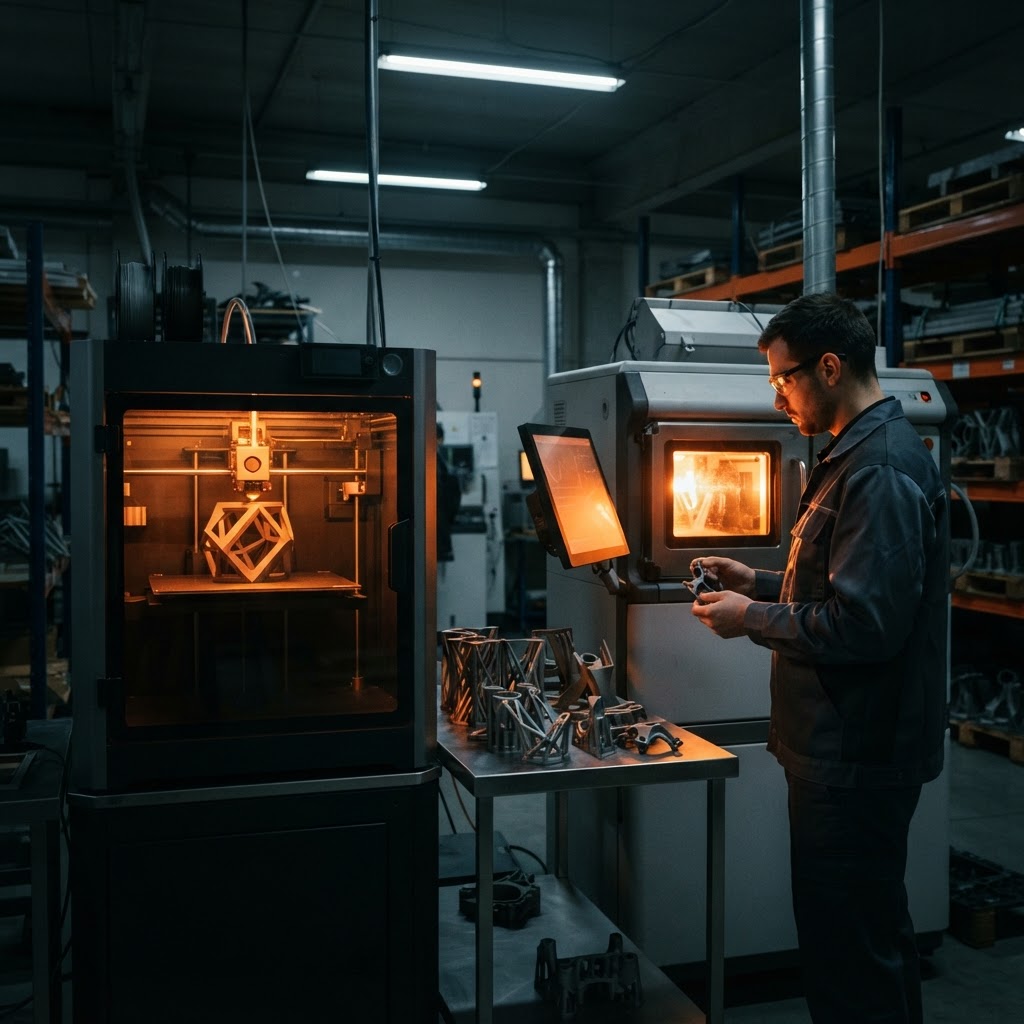
Polymer and metal additive manufacturing share a family name and almost nothing else. The decision tree between them begins with load-bearing requirements and ends with a certification burden that can dwarf the capital cost of the machine itself. Polymer processes — primarily Fused Deposition Modeling (FDM), Selective Laser Sintering (SLS), and Stereolithography (SLA) — excel in producing low-weight, geometrically complex components where structural demand is modest: ducting, brackets, crew-compartment housings, ground support equipment, and tooling fixtures. Metal processes — Laser Powder Bed Fusion (LPBF), Directed Energy Deposition (DED), and Binder Jetting — operate in a different physical and regulatory universe entirely.
The Department of Defense has spent the better part of a decade attempting to codify the difference through qualification frameworks. MIL-SPEC compliance for additively manufactured metal flight-critical parts remains one of the most demanding qualification pathways in American manufacturing. The Air Force Research Laboratory (AFRL) has invested heavily in Integrated Computational Materials Engineering (ICME) approaches specifically to shorten that runway — but shorten it from years to months, not days.
For operations directors evaluating capital allocation decisions in late 2026, the practical split looks like this:
- Polymer AM is production-ready today for non-structural components, tooling, and low-volume spares with lead times measured in days rather than months
- Metal AM is production-viable for structural and semi-structural components where the geometry justifies the qualification investment and the part count is insufficient to warrant traditional casting or forging tooling
- Neither process is a wholesale replacement for subtractive manufacturing — a point the industry has been slowly absorbing since the early hype cycle of 2012–2018
Where Metal AM Has Actually Landed in Defense Production
GE Aerospace did not print the LEAP fuel nozzle as a technology demonstration. It printed it because consolidating nineteen traditionally manufactured components into one reduced weight by 25 percent and increased durability fivefold — and because the economics at production volumes justified the qualification cost. That is the calculus defense primes now apply before committing to metal AM at scale.
Raytheon Technologies, Lockheed Martin, and L3Harris have each disclosed additive manufacturing integration across missile systems, sensor housings, and propulsion components — though the specific programs frequently carry classification that prevents the kind of granular public reporting this publication would prefer. What is publicly known: the Joint Strike Fighter program has qualified over 900 additively manufactured parts for the F-35, a figure that carries weight precisely because the F-35's certification standards are among the most rigorous in Western aerospace.
The Navy's Additive Manufacturing Center of Excellence in Portsmouth, Virginia has demonstrated shipboard production of metal components — reducing certain spare part lead times from eighteen months to under seventy-two hours. It is a useful proof point, though one should note that replacing a pipe flange on a destroyer is a different qualification burden than replacing a turbine blade on a carrier-based fighter. The Navy knows this. The point is logistics compression, not structural equivalence.
"The certification burden for metal AM flight-critical parts does not disappear because the printer is faster — it transfers from the foundry to the quality management system, and most Tier 2 shops are not ready for that transfer."

What will it take to turn demand into delivered output?
Explore The Capacity Imperative, our report on U.S. advanced manufacturing and the priorities shaping 2027.
Polymer AM's Underappreciated Production Role
The defense industrial base's fixation on metal printing has obscured a quieter, arguably more immediately scalable story: high-performance polymer AM has become a genuine production technology for a class of components that previously required expensive injection mold tooling with lead times of twelve to twenty weeks. Stratasys ULTEM 9085-based FDM components have achieved FAA and USAF flight certification. SABIC's aerospace-grade thermoplastics have enabled structural brackets at weights competitive with aluminum for secondary structure applications.
DARPA's Resin Printing at Commercially Competitive Costs (RP3C) program reflects institutional acknowledgment that polymer AM's economics, at sufficient scale and material maturity, can compress the cost per part for certain defense components below traditional manufacturing. The program's implications for small satellite structure, UAV airframe components, and expendable munitions housings are not theoretical — they are procurement-relevant within the current FY2027 defense budget cycle.
SLM and LPBF receive the headlines. Continuous Fiber Reinforcement (CFR) polymer printing — pioneered commercially by Markforged — is receiving the purchase orders. For non-structural secondary components with complex geometry and tight lead time requirements, this technology tier is mature, certifiable, and cost-effective today. It does not require a $2 million LPBF system or an inert gas management infrastructure.
The Qualification Architecture Is the Real Differentiator
Manufacturing executives evaluating additive processes in 2026 must understand that the machine is not the investment — the quality management system surrounding it is. AS9100 certification is table stakes. What separates production-capable additive shops from job shops with expensive printers is the documented process qualification package: material traceability from powder lot to finished part, non-destructive evaluation (NDE) protocols adapted for AM geometry, and a first-article inspection regime that satisfies DCSA and prime contractor flow-down requirements simultaneously.
This is where the polymer-versus-metal distinction becomes an organizational question as much as a technical one. Polymer production AM can be stood up within an existing ISO 9001 or AS9100 framework with modest incremental investment in process documentation. Metal AM qualification — particularly for flight-critical structure — requires dedicated metallurgical testing capacity, powder handling protocols, and an NDE capability that most Tier 2 and Tier 3 shops will need to either build or partner to access.
What This Means for Tier 2 and Tier 3 Suppliers
The strategic implications for lower-tier defense manufacturers are specific and time-sensitive. The DoD's accelerating push toward organic manufacturing capacity — driven by supply chain vulnerability lessons absorbed from both the COVID disruption and the Ukraine conflict's materiel demands — creates a near-term window for qualified additive suppliers. Here is where to focus:
-
Qualify polymer AM for tooling and non-structural spares first. This is the fastest path to a billable AM capability within existing quality systems. Demand for additively manufactured ground support equipment, jigs, and maintenance tooling is immediate and poorly served across the defense supply chain.
-
Assess the metal AM partnership model before the capital model. Most Tier 2 shops cannot justify a $1.5M–$3M LPBF system on current volume projections. Service bureau partnerships with qualified metal AM providers — Velo3D, Sintavia, or Carpenter Additive — allow participation in metal AM programs while qualification investment scales with actual demand.
-
Invest in qualification documentation now, not after the contract. Primes awarding additive manufacturing work under Other Transaction Authority (OTA) agreements and IDIQ vehicles are selecting suppliers based on existing qualification packages, not promises of future compliance.
-
Monitor the AFRL's Metals Affordability Initiative and DARPA RP3C for funded qualification assistance. Both programs have historically provided cost-share mechanisms that offset qualification investment for smaller manufacturers with demonstrated production intent.
-
Differentiate between production AM and prototype AM in your business development language. The DoD contracting community has grown sophisticated enough to discount suppliers who conflate the two. A shop with a production-qualified polymer AM cell and documented process control is a more credible supplier than one with a newer machine and no qualification history.
The operational tempo of American defense procurement in 2026 does not reward manufacturers who treat additive as a future capability. The programs are funded, the parts lists are growing, and the qualification barriers — while real — are not insurmountable for suppliers willing to invest in process discipline before the solicitation drops.
Sources: Air Force Research Laboratory · DoD Additive Manufacturing Roadmap · Naval Sea Systems Command · SAE AS9100 Standard · DARPA Program Information

