Why Aerospace Supply Chains Are Going Vertical in 2026
The last time American aerospace primes moved this aggressively to pull supplier capabilities in-house, the Cold War was providing the motivation and the Pentagon was writing blank checks. Today's calculus is different - and in some ways more clarifying. No single geopolitical crisis is driving vertical integration in 2026. Instead, it's the accumulated weight of years of supply chain fragility, escalating lead times, a defense budget under structural pressure, and the quiet recognition among program managers that the lean, distributed supplier model the industry spent three decades perfecting was also, as it turned out, a single point of failure waiting to be stress-tested.
It got stress-tested. The industry is still recovering.
The Fragility That Couldn't Be Hidden
The Boeing 737 MAX crisis, the COVID-era shutdown of tier-two and tier-three suppliers, the Spirit AeroSystems turbulence - these weren't isolated shocks. They were diagnostic events that revealed something the industry had chosen not to examine too closely: deep-tier supplier dependency at a scale that made program schedules genuinely hostage to single-source vendors producing relatively modest components. A missing door plug. A fastener shortage. A composite fabricator in a regional industrial park that quietly lost its workforce during a pandemic and never fully rebuilt it.
For operations directors who lived through the 2022–2024 delivery crises at both Boeing and Airbus, the lesson was visceral. Outsourcing for cost efficiency works precisely until it doesn't, and when it fails in aerospace, it fails expensively, publicly, and with FAA investigators in the building.
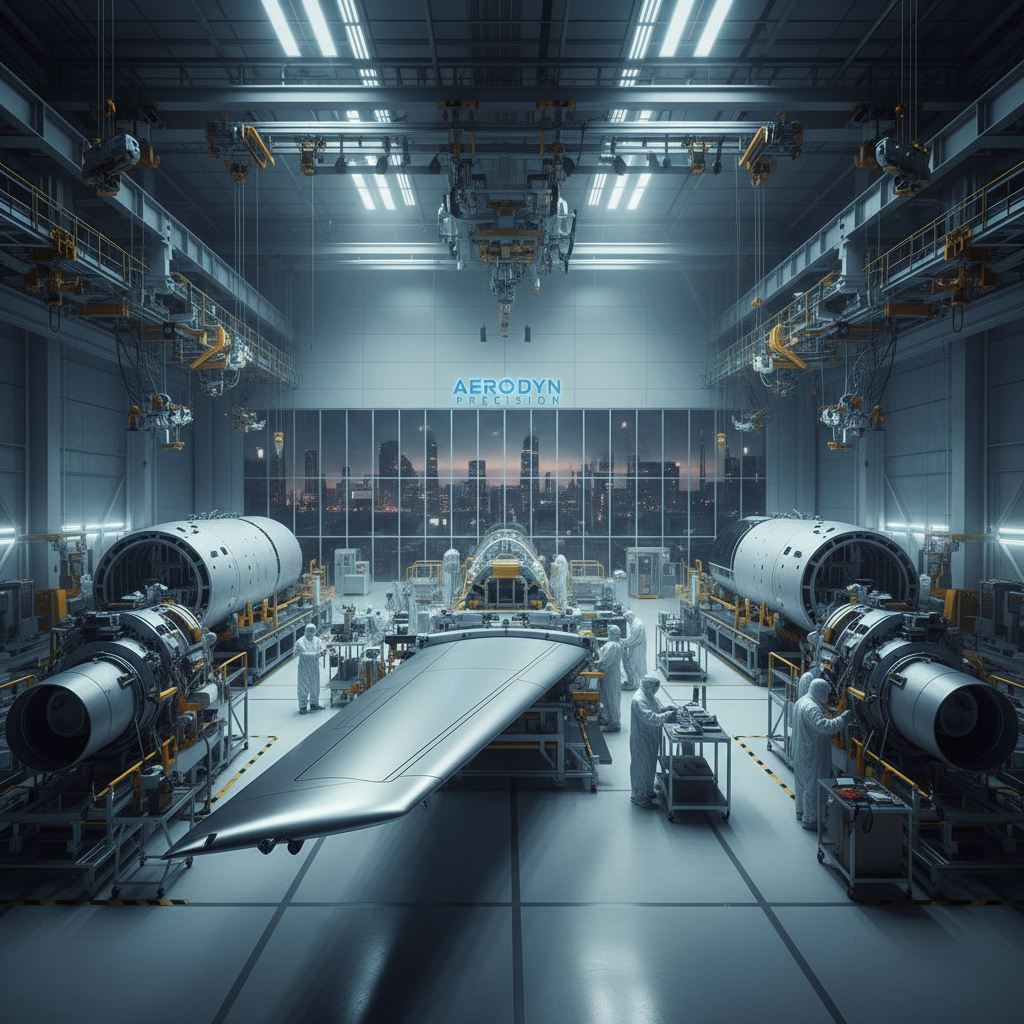
The response, now solidifying into capital allocation decisions and M&A strategy across the sector, is a measured but unmistakable move toward vertical integration - the deliberate decision to own more of the value chain rather than contract it.
What Vertical Integration Actually Means in This Context
It's worth being precise here, because the term gets used loosely. Vertical integration in 2026 aerospace doesn't mean every prime contractor is building their own aluminum smelter. It means something more surgical:
- Acquiring critical subtier suppliers whose capabilities represent bottlenecks or single-source dependencies
- Investing in internal manufacturing cells for components previously sourced externally - particularly in composites, precision machining, and advanced electronics
- Bringing quality and process control upstream, so that defects are caught inside the organization rather than at receiving inspection
- Reducing geographic and geopolitical exposure in the supply base, particularly for components touching ITAR-controlled systems
Raytheon's parent RTX has been explicit about its intent to reduce supplier dependency on certain castings and forgings after program delays tied to external vendors became a recurring theme on earnings calls. L3Harris has made similar moves in the electronics and sensor space. On the commercial side, Boeing's reacquisition of Spirit AeroSystems' core fuselage operations - however fraught the execution - represents the clearest statement that the outsourcing experiment for primary structures has reached its limits.
None of these moves are cheap. All of them reflect a leadership consensus that the cost of supply chain fragility now exceeds the cost of vertical integration.
The Defense Industrial Base as Forcing Function
For defense-facing manufacturers, the pressure is coming from an additional direction: the Pentagon itself. The Defense Department's ongoing assessments of industrial base vulnerabilities - formalized through National Defense Authorization Act provisions and the work of the Office of Strategic Capital - have made it increasingly clear that the government views subtier supply chain consolidation as a national security issue, not merely a commercial one.
Programs like the F-35, the B-21 Raider, and the emerging Next Generation Air Dominance platform carry delivery schedules that the services treat as strategic commitments. When a tier-three supplier producing a specialty alloy component goes dark, the ripple effect isn't just a delayed aircraft - it's a gap in operational readiness planning that reaches into combatant command war rooms. That's a different kind of stakeholder pressure than a nervous investor on a quarterly call.
The result is that prime contractors on major defense programs are increasingly being evaluated - informally but consequentially - on the depth and stability of their supply chains, not just their own manufacturing performance. Lockheed Martin and Northrop Grumman both understand this. Their supplier development programs have quietly evolved from cost-reduction exercises into something closer to industrial policy implementation.

What will it take to turn demand into delivered output?
Explore The Capacity Imperative, our report on U.S. advanced manufacturing and the priorities shaping 2027.
Capital Intensity and the Make-vs-Buy Recalculation
The honest complication in all of this is that vertical integration is expensive, and aerospace manufacturing is already one of the most capital-intensive industries in the American economy. Building internal capability in precision machining, composite lay-up, or advanced avionics fabrication requires equipment investment, workforce development, and the kind of institutional patience that quarterly earnings cycles don't naturally reward.
This is where the 2026 environment differs meaningfully from previous cycles. Several factors are making the capital case easier to close:
- Reshoring incentives under the CHIPS and Science Act framework, extended manufacturing tax provisions, and defense-specific procurement preferences for domestically sourced components are shifting the financial math on internal investment
- Advanced manufacturing technology - particularly in additive manufacturing, automated composite fabrication, and digital inspection systems - has materially reduced the cost of standing up new internal capability versus what it would have required a decade ago
- Workforce consolidation logic: bringing production in-house allows manufacturers to concentrate skilled labor in controlled environments rather than competing for it across a fragmented supplier base
The make-vs-buy analysis that used to reliably favor outsourcing for anything below a certain complexity threshold is returning different answers now. Plant managers running those models are finding that the fully-loaded cost of external sourcing - including expedite fees, quality escapes, schedule buffer requirements, and the overhead of supplier surveillance - has risen substantially while the cost of internal capability has declined on a relative basis.
What This Looks Like on the Shop Floor
For operations directors and plant managers, the vertical integration trend has immediate, concrete implications that go beyond strategic positioning.
First, capacity planning becomes more complex. When you absorb a previously outsourced manufacturing step, you inherit its demand variability and its interaction with your existing production flow. The integration work - tooling, fixtures, process qualification, first article inspection - takes longer than leadership timelines typically anticipate. Building in realistic transition periods isn't pessimism; it's the difference between a successful insourcing and a quality escape six months after program launch.
Second, workforce planning moves to center stage. Vertical integration only delivers value if the internal team can execute at or above the quality level of the supplier being replaced. In an environment where skilled machinists, composites technicians, and quality engineers are scarce, this is not a small assumption. Companies that are executing well on this - GE Aerospace's manufacturing expansion in Ohio, Textron's internal capability build-out in its Bell and Cessna divisions - are doing so because they started the workforce development work two to three years before they needed the capacity.
Third, and perhaps most importantly for this readership: the ERP and MES infrastructure has to keep up. Vertical integration collapses the organizational distance between design, procurement, and production. If your manufacturing execution systems can't handle the increased complexity of internal work orders, traceability requirements, and first article documentation for newly insourced processes, you will find yourself with more capability and less throughput. That's a failure mode worth spending serious attention on before the first workorder drops.
The Consolidation Wave and What Comes After
The M&A dimension of this trend deserves a final note. Vertical integration through acquisition - rather than organic capability development - is accelerating, and the targets are primarily mid-market precision manufacturers, specialty material processors, and niche electronics houses that have operated quietly as tier-two and tier-three suppliers for decades. For those companies, the current environment represents either an opportunity or an existential pressure, depending on their strategic position and ownership structure.
For the primes and upper-tier contractors doing the acquiring, the discipline question is whether the integration work gets done properly or whether these acquisitions become expensive overhead with a different organizational chart. The history of aerospace M&A is littered with capability acquisitions that looked compelling on a capabilities matrix and underdelivered because the operational integration was handled as an afterthought.
The supply chain that emerges from this cycle will be shorter, more controlled, and almost certainly more expensive in its fixed cost structure than the distributed model it replaces. The bet being placed - by RTX, by Boeing, by Lockheed, by a dozen mid-size defense contractors - is that reliability, schedule performance, and geopolitical durability are worth that premium. Given what the last four years demonstrated about the alternative, it's a bet that's very hard to argue against. The question now is purely one of execution - and in aerospace manufacturing, execution is always where theory goes to be tested.

