
Government and Industry Accelerate Investments in Advanced Manufacturing and Technology: What Manufacturing Leaders Need to Know This Week
By Marcus D. Holloway, Editor in Chief, Strata Intelligence | August 28, 2026
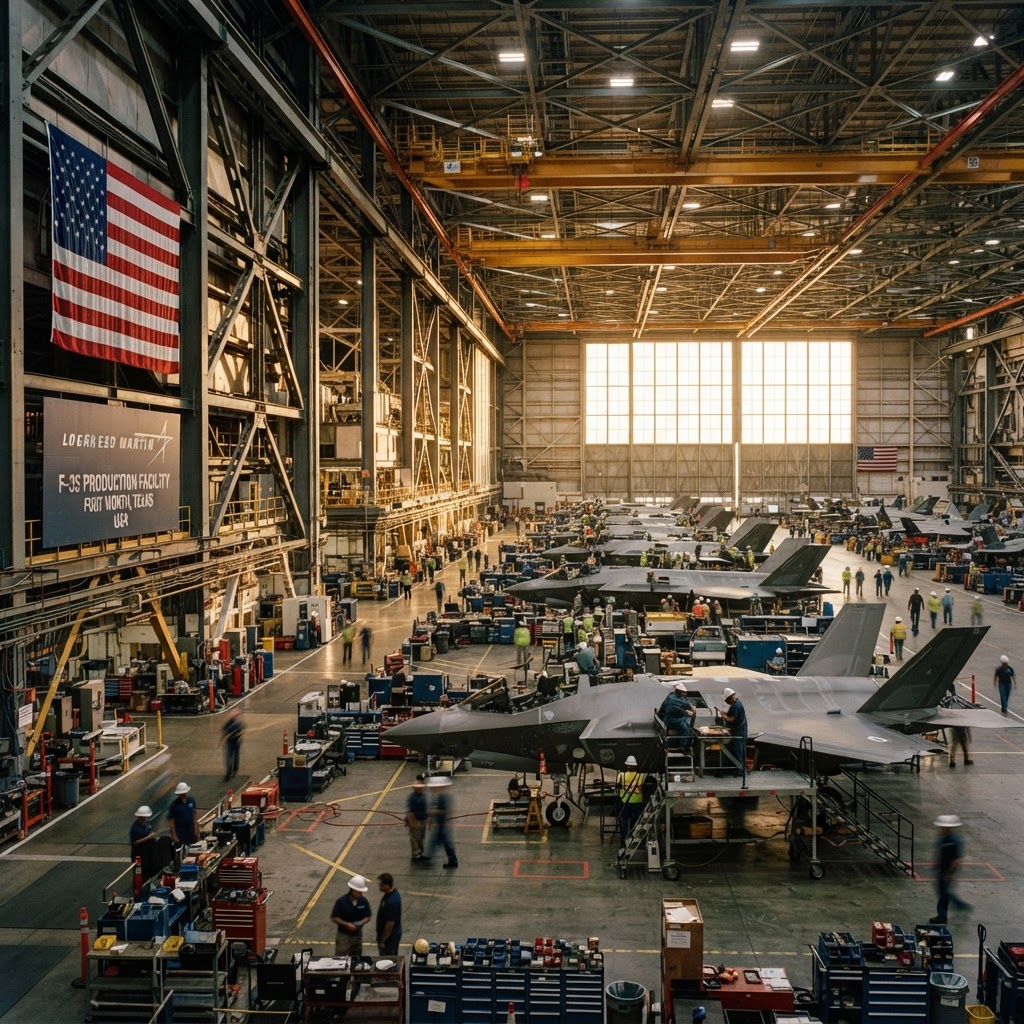
The United States industrial base is undergoing a structural transformation this week — not incrementally, but through simultaneous, coordinated moves by the federal government and major industrial players that will reshape supply chains, redefine defense manufacturing, and set the competitive ceiling for the next decade of domestic production.
Executive Summary
Four developments landed this week with compounding significance for manufacturing leadership:
- Eaton Corporation completed its acquisition of Boyd Thermal, cementing a full grid-to-chip power and thermal solution for AI-era data centers.
- The US Department of Defense launched a first-of-its-kind manufacturing pilot under the Defense Production Act, introducing private capital into defense industrial scaling.
- The US Department of Commerce took a direct equity stake in GlobalFoundries to anchor domestic quantum manufacturing capability.
- The DoD and DoC jointly committed up to $3 billion to Intel Corporation for a dedicated Secure Enclave for national-security-grade semiconductor fabrication.
Read these four events in isolation and you see corporate M&A and government grants. Read them together and you see the architecture of a reindustrialized America being built in real time.
Eaton's Boyd Thermal Acquisition Signals the Infrastructure Imperative Behind AI
Eaton Corporation has completed its acquisition of Boyd Thermal, a leading provider of liquid-cooling solutions, creating what the company describes as an industry-leading grid-to-chip infrastructure platform for modern data centers. Read more
For plant operators and procurement directors watching the industrial supply chain, this deal is not a sideshow. It is a direct response to one of the most acute infrastructure crises in manufacturing history: the thermal density problem created by AI factory deployments.
Here is what the acquisition means across three time horizons:
Immediate implications:
- Eaton now controls a unified solution from utility-level power management down to chip-level thermal control — a single-vendor proposition that dramatically simplifies procurement for hyperscale data center operators.
- Suppliers in the mechanical and electrical contractor space will face consolidated purchasing pressure; Eaton's enhanced integrated offering reduces the number of vendors required in a data center build-out.
- Facility managers and MEP engineers planning high-density AI compute deployments now have a single accountability line for power and cooling performance.
Downstream implications:
- This acquisition will accelerate consolidation across the data center infrastructure supply chain. Smaller, specialized thermal management vendors who have not already aligned with a power management platform will face intensifying margin pressure and acquisition interest within the next 18 to 24 months.
- For US manufacturers supplying components into data center builds — whether coolant distribution units, heat exchangers, or power distribution equipment — the Eaton-Boyd Thermal integration raises the specification floor. Suppliers who cannot meet integrated system interoperability requirements will be disqualified from Tier 1 project bids.
- The transaction validates liquid cooling as a non-negotiable infrastructure category, not an optional premium. Any manufacturing organization planning capital facilities for high-performance computing must now budget for liquid-cooled architecture from the design phase.
"The thermal density problem created by AI factory deployments is not a cooling problem — it is a systems integration problem, and Eaton just acquired the missing half of its answer."
The DoD's DPA Pilot Introduces a New Capital Model for Defense Manufacturing
The US Department of Defense launched a manufacturing pilot program under the Defense Production Act Title III Program in partnership with the Austin Center for Manufacturing and Innovation (ACMI). Read more
The program's design is structurally significant: it introduces private capital as an accelerant inside a federal manufacturing framework. This is not a traditional government contract or a cost-plus production agreement. It is a new model — one that allows commercial incentives and defense readiness requirements to operate on the same runway.
For manufacturing leaders, the operational implications break down as follows:
What this program does differently:
- Leverages private capital to scale advanced manufacturing technology rather than relying exclusively on appropriated federal funding.
- Targets both commercial and military applications simultaneously, creating a dual-use production mandate that justifies larger investment commitments from private sector partners.
- Establishes ACMI as a prototype for regional manufacturing innovation hubs that can be replicated across the industrial base.
Supplier and plant-operator action points:
- Defense-adjacent manufacturers in advanced materials, additive manufacturing, and precision machining should treat this pilot as an early signal of a broader procurement philosophy shift. DoD is moving toward co-investment models, which means vendors who can bring capital and capability — not just capacity — will be prioritized.
- For procurement directors, this signals that the traditional defense subcontractor relationship is evolving. Strategic alignment with innovation hubs like ACMI may become a prerequisite for future program access.
- C-suite executives in industrial manufacturing should monitor DPA Title III Program activity closely. As this pilot demonstrates results, expect the model to be scaled with larger capital commitments and broader technology mandates.

What will it take to turn demand into delivered output?
Explore The Capacity Imperative, our report on U.S. advanced manufacturing and the priorities shaping 2027.
Commerce's Equity Stake in GlobalFoundries Rewrites the Rules of Industrial Policy
The US Department of Commerce has taken an approximately 1% strategic equity stake in GlobalFoundries as part of a broader initiative to scale domestic quantum manufacturing under CHIPS Act Research and Development investments. Read more
This is the sharpest policy instrument deployed this week, and it demands careful attention from every executive operating in or adjacent to the semiconductor supply chain.
The federal government taking a direct equity position in a private manufacturing company is not a grant, a loan, or a tax incentive. It is a statement of long-term alignment — the government as a stakeholder, not merely a regulator or customer. The implications of this posture are consequential:
Immediate implications:
- GlobalFoundries now has a federally aligned mandate to scale quantum technology solutions domestically, with Commerce positioned to share in the financial returns. This creates an accountability structure that differs fundamentally from grant-based relationships.
- Suppliers into GlobalFoundries' quantum fabrication lines — specialty gases, advanced lithography equipment, process chemicals — should expect accelerated volume commitments as the quantum manufacturing scale-up progresses.
- Competing foundries and semiconductor manufacturers operating domestically will face pressure to demonstrate equivalent strategic alignment with federal priorities or risk being structurally disadvantaged in future government procurement and investment decisions.
Downstream implications:
- This model — government equity participation in critical technology manufacturers — may become a template. Manufacturing executives in defense electronics, advanced materials, and photonics should prepare for the possibility that federal equity participation becomes a standard instrument in the CHIPS-era industrial policy toolkit.
- For procurement directors sourcing quantum-compatible components, GlobalFoundries' accelerated domestic buildout will improve supply chain optionality within a two-to-four-year window, reducing current dependence on international quantum fabrication capacity.
Intel's $3 Billion Secure Enclave Mandate Sets the Floor for Defense Semiconductor Sovereignty
In the single largest defense-industrial commitment of the week, the US Department of Defense and US Department of Commerce issued a joint statement announcing up to $3 billion in direct funding to Intel Corporation under the CHIPS and Science Act. The funding will establish a dedicated Secure Enclave for the fabrication of advanced microelectronics serving national security requirements. Read more
The Secure Enclave concept is not new in defense acquisition theory, but this funding commitment operationalizes it at a scale that restructures the entire defense electronics supply chain.
What the Secure Enclave means for manufacturing leaders:
- Supply chain segmentation becomes permanent: Defense-grade semiconductor fabrication will operate in physically and procedurally isolated facilities. Manufacturers supplying into defense electronics programs must begin evaluating whether their components can achieve or maintain Secure Enclave compatibility standards.
- Domestic sourcing mandates will tighten: With a federally funded, domestically secured fabrication pathway now funded, defense prime contractors and their sub-tier suppliers will face accelerating buy-American enforcement. Procurement directors sourcing any semiconductor content for defense programs should audit foreign-origin exposure now.
- Intel's competitive positioning shifts: The Secure Enclave designation gives Intel a structural advantage in the defense electronics market that is not replicable through commercial investment alone. Competing foundries seeking defense program access will need to demonstrate equivalent security and domestic manufacturing credentials.
- Workforce implications: The buildout of a Secure Enclave facility at Intel's scale will require a specialized, security-cleared manufacturing workforce. Talent acquisition in advanced semiconductor process engineering, particularly for cleared personnel, will intensify significantly over the next 24 months.
For C-suite executives across the defense industrial base, this funding announcement is both a ceiling and a floor: the ceiling on foreign semiconductor dependency for classified programs has effectively been set, and the floor for domestic advanced manufacturing investment is now defined.
Editor's Take: The 90-Day Outlook
What we witnessed this week is not a collection of unrelated announcements. It is the convergent execution of an industrial strategy that has been assembling for three years under the CHIPS Act framework, Defense Production Act authorities, and accelerating AI infrastructure demand. The pace has changed.
For manufacturing leaders, the 90-day outlook resolves into three concrete imperatives:
1. Audit your supply chain for federal alignment gaps. The GlobalFoundries equity stake and the Intel Secure Enclave funding are opening shots in a longer campaign to segment the US industrial base into federally aligned and non-aligned tiers. Organizations that are not actively mapping their exposure to these programs — whether as potential beneficiaries or as displaced suppliers — are operating with incomplete strategic intelligence.
2. Reassess your data center infrastructure strategy immediately. Eaton's Boyd Thermal acquisition collapses the timeline on liquid-cooling adoption from an aspirational roadmap item to a current procurement decision. If your organization operates, builds, or supplies into high-performance computing facilities and your thermal strategy still centers on air cooling, that strategy is functionally obsolete for AI-density workloads.
3. Position for co-investment, not just contract pursuit. The DoD's DPA pilot with ACMI signals that the next generation of defense manufacturing relationships will require manufacturers to bring capital alongside capability. Organizations that treat defense manufacturing as a pure revenue pursuit without strategic co-investment will find themselves outside the preferred vendor architecture that this new model is constructing.
The reindustrialization of America is no longer a policy ambition. It is an operational reality, and it is moving faster than most manufacturing organizations have planned for.
Sources: Eaton Corporation News Releases · GlobalFoundries Quantum Technology Solutions Announcement · DoD/DoC Joint Statement on Intel CHIPS Funding · DoD DPA Manufacturing Pilot Program Release · CHIPS and Science Act – NIST

