
Defense Modernization and Labor Negotiations Shape the Aerospace Manufacturing Sector: What Manufacturing Leaders Need to Know This Week
By Marcus D. Holloway, Editor in Chief, Strata Intelligence | July 4, 2026
The week ending July 4, 2026 delivered a concentrated dose of structural signals for the aerospace and defense manufacturing sector — five major developments across five premier contractors that collectively redefine production priorities, labor dynamics, and supply chain pressure for the next five years. For C-suite leaders, plant managers, and procurement directors, the message is unambiguous: the defense industrial base is accelerating, and the organizations that position now will capture the margin; those that hesitate will chase capacity they cannot find.
Executive Summary
This briefing covers five material developments:
- Boeing enters formal contract negotiations with 17,000 engineers and technical workers under a novel interest-based bargaining model ahead of an October 2026 contract deadline.
- Lockheed Martin secures a $3 billion framework agreement for Sentinel A4 radar station production through 2031.
- L3Harris Technologies locks in a contract to modernize 700-plus FAA ground stations through 2045.
- Northrop Grumman receives a $312.3 million Navy contract modification for SEWIP Block 3 electronic warfare systems.
- Raytheon Technologies finalizes a $1.1 billion Navy contract to manufacture AIM-9X Block II missiles at a rate of 2,500 units annually.
Taken individually, each is significant. Taken together, they constitute a coherent strategic picture: the U.S. defense industrial base is simultaneously expanding capacity, locking in long-horizon revenue, and confronting workforce risk at scale.
Boeing's Labor Gamble: Interest-Based Bargaining Is Either a Lifeline or a Distraction
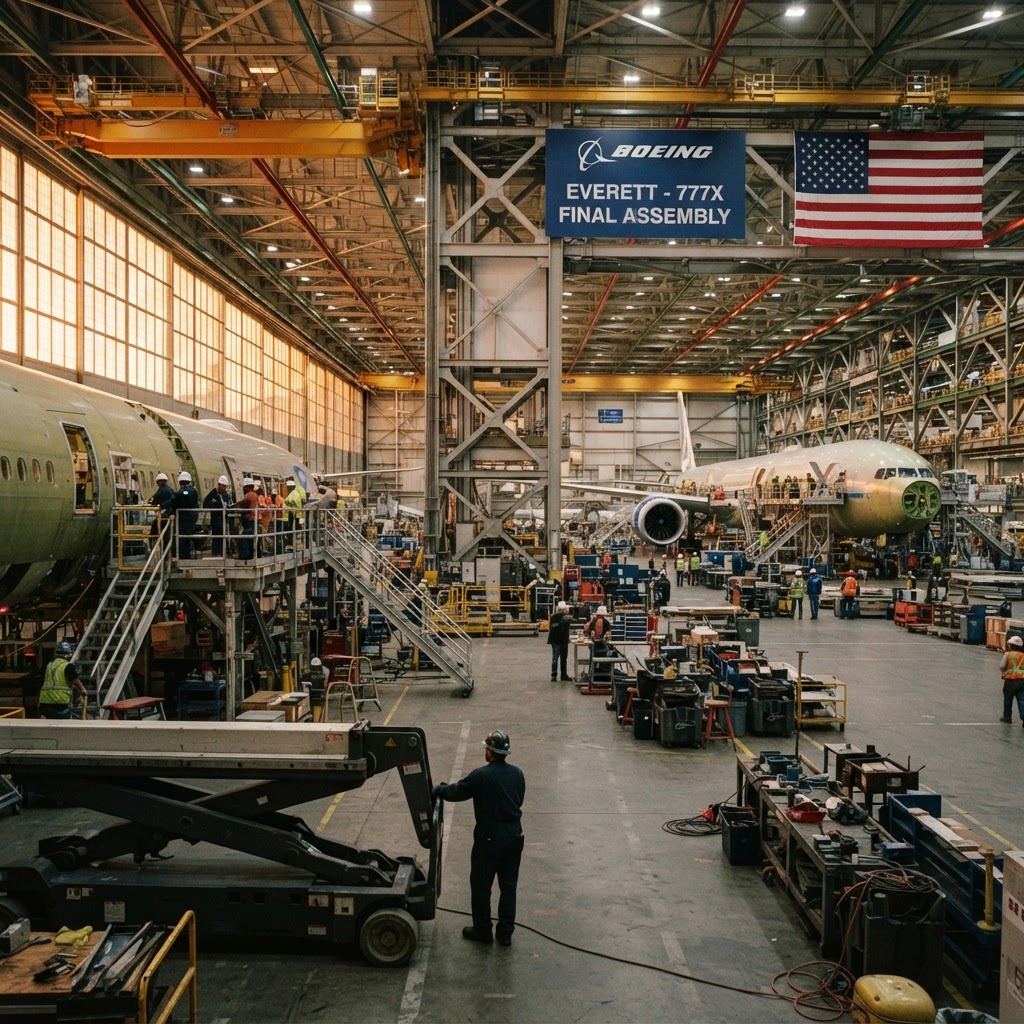
Boeing began formal contract negotiations this week with the Society of Professional Engineering Employees in Aerospace (SPEEA), the union representing approximately 17,000 engineers and technical workers. Contracts expire in October 2026. Crucially, the parties have elected to use an interest-based bargaining (IBB) methodology — a collaborative, consensus-driven alternative to traditional adversarial negotiation — signaling that Boeing's leadership recognizes the catastrophic cost of another labor disruption. Read more
The downstream implications for manufacturers and suppliers are direct and consequential:
- Production rate risk is live. Boeing's ability to increase 737 MAX and 787 production rates — a prerequisite for restoring commercial aviation supply chains — is contingent on engineering workforce stability. A work stoppage involving 17,000 engineers would halt not just assembly but design iteration, quality assurance, and certification work simultaneously.
- Supplier scheduling windows are exposed. Tier 1 and Tier 2 suppliers who have aligned their own hiring and capital expenditure plans to Boeing ramp projections must monitor this negotiation as a leading indicator. Any breakdown in IBB talks before October shifts those ramp timelines materially.
- IBB is not a guarantee. Interest-based bargaining produces better outcomes when both parties enter with genuine flexibility on interests rather than fixed positions. Boeing's financial recovery trajectory — and the union's awareness of that trajectory — creates pressure on both sides. The method is promising; the outcome is not predetermined.
- Quality remediation depends on this workforce. Post-crisis quality improvement programs at Boeing are engineering-intensive. The same SPEEA-represented workers who are negotiating this contract are the ones executing the corrective action plans regulators are watching.
"Boeing's turnaround does not happen without its engineers — and this negotiation is the single variable that could accelerate or derail every other production commitment the company has made."
For plant operators in the extended Boeing supply chain, the 90-day window before contract expiration is the planning horizon. Build contingency into your Q4 delivery schedules now.
Lockheed's Sentinel A4 Win: Multiyear Radar Production Locks In Domestic Manufacturing Demand
Lockheed Martin signed a framework agreement with the U.S. Department of Defense worth up to $3 billion for the production and delivery of Sentinel A4 radar stations through June 2031. The agreement covers domestic production requirements and preserves optionality for international Foreign Military Sales demand. Read more
For manufacturing leaders, the structural implications are threefold:
- Multiyear contracts create supplier predictability. A five-year production agreement of this scale allows Lockheed's radar subsystem and component suppliers to make capital investment decisions with confidence. Expect Lockheed to issue multi-release purchase orders that will propagate down to antenna array fabricators, power electronics suppliers, and systems integrators.
- International demand is an amplifier, not a hedge. The framework explicitly contemplates future international sales. Given the current NATO rearmament cycle and Indo-Pacific air defense investment, the probability of FMS orders materializing before 2031 is high. Suppliers should size capacity for upside, not just the base domestic program.
- Workforce implications are real. A sustained five-year production run requires stable manufacturing labor — precisely the kind of long-horizon commitment that justifies apprenticeship programs, capital tooling, and facility expansion for both Lockheed and its Tier 2 partners.

What will it take to turn demand into delivered output?
Explore The Capacity Imperative, our report on U.S. advanced manufacturing and the priorities shaping 2027.
L3Harris Secures the FAA's Backbone: A 2045 Infrastructure Contract Changes the Civilian Revenue Equation
L3Harris Technologies received a long-term contract from the Federal Aviation Administration to upgrade and operate the national aircraft tracking network through 2045. The scope includes modernization of over 700 ground stations providing real-time, satellite-based flight positioning data — the foundational infrastructure of U.S. airspace management. Read more
This contract is analytically distinct from the defense awards dominating this week's headlines, and that distinction matters enormously:
- Revenue diversification at scale. L3Harris has historically derived the substantial majority of its revenue from defense contracts subject to annual appropriations cycles. A nearly two-decade civilian infrastructure contract provides a structurally different revenue stream — one insulated from defense budget fluctuations and continuing resolutions.
- Operations and maintenance creates recurring cash flow. Unlike a production contract with a defined delivery schedule, an operate-and-maintain agreement generates revenue continuously across the contract term. For procurement directors evaluating L3Harris as a supplier partner, this signals financial stability and balance sheet strength.
- Workforce profile shifts. Modernizing and operating 700-plus ground stations requires field technicians, network engineers, and systems administrators — a talent profile meaningfully different from defense electronics engineers. Expect L3Harris to expand hiring in aviation systems and network operations disciplines over the next 24 months.
- Supplier implications for ground station components. The modernization phase will drive near-term procurement of communications hardware, ruggedized computing platforms, and antenna systems. Suppliers with FAA-certified components and civilian aviation pedigree should be positioning now.
The strategic takeaway for the sector: L3Harris has just insulated roughly two decades of its revenue base from the defense appropriations volatility that will define the next several congressional cycles.
Northrop and Raytheon: Electronic Warfare and Tactical Munitions Signal a Supply Chain Under Pressure
Two contracts awarded in the final days of June complete this week's picture and must be read together, because their combined effect on the defense electronics supply chain is greater than either signals independently.
Northrop Grumman secured a $312.3 million contract modification from the U.S. Navy for continued production of Surface Electronic Warfare Improvement Program (SEWIP) Block 3 systems, with work anticipated through August 2029. Read more
Raytheon Technologies finalized a $1.1 billion Navy contract modification to manufacture AIM-9X Block II short-range missiles, expanding engineering headcount in Arizona and targeting production capacity of 2,500 missiles annually. Read more
For manufacturing and procurement leaders, the critical analysis sits at the intersection of these two contracts:
Electronic Components Under Compression
- SEWIP Block 3 is a sophisticated naval electronic warfare platform requiring high-grade gallium nitride semiconductors, advanced RF components, and specialized signal processing hardware. Northrop's backlog expansion tightens availability of these components across the broader defense electronics supply chain.
- AIM-9X Block II missile production at 2,500 units per year is a volume-intensive manufacturing commitment. At that rate, Raytheon's suppliers of guidance electronics, infrared seekers, and propulsion components will be operating at or near capacity.
- Procurement directors at any company competing for similar components — surveillance systems, precision-guided munitions, electronic countermeasures — should treat this week's contracts as a demand signal and accelerate long-lead component procurement strategies immediately.
Workforce Expansion Creates Regional Labor Competition
- Raytheon's Arizona engineering workforce expansion will intensify competition for defense electronics engineers, systems integrators, and quality assurance professionals in the Phoenix-Tucson corridor. Regional manufacturers and suppliers in that geography should expect wage pressure.
- Northrop's SEWIP work running through 2029 similarly anchors a trained technical workforce to that program's facilities, reducing the available pool for adjacent defense programs.
The Combined Signal When a $312 million electronic warfare contract and a $1.1 billion munitions contract land within 72 hours of each other, both drawing on overlapping component ecosystems and engineering talent pools, the message to supply chain planners is unambiguous: the window to secure favorable terms on long-lead defense components is closing.
Editor's Take: Marcus D. Holloway's 90-Day Outlook
Looking at this week's developments as a portfolio rather than isolated events, three structural conclusions emerge for the 90-day horizon.
First, labor is the dominant risk variable. Every production acceleration story in this briefing — Boeing's rate increases, Raytheon's missile ramp, Lockheed's five-year radar run — depends on qualified human beings performing skilled technical work. The Boeing-SPEEA negotiation is the most visible flashpoint, but it is symptomatic of a sector-wide condition: the defense industrial base is expanding faster than the available workforce can scale. Plant managers who are not actively running apprenticeship pipelines, retention incentive programs, and cross-training initiatives today will be paying premium agency labor costs by Q1 2027.
Second, the civilian-defense revenue boundary is dissolving for the smartest contractors. L3Harris's FAA contract is the clearest example this week, but it reflects a broader strategic logic: companies that can diversify revenue across defense, civilian infrastructure, and dual-use technology are building resilience that pure-play defense manufacturers cannot match. Procurement directors evaluating supplier financial health should weight this diversification as a positive indicator.
Third, component lead times are about to lengthen. The combination of Northrop's SEWIP ramp and Raytheon's AIM-9X expansion — layered on top of ongoing HIMARS and Patriot production demands — is creating compressive pressure on the defense electronics supply chain that will manifest in extended lead times for gallium nitride components, precision RF hardware, and guidance electronics within 60 to 90 days. Act on procurement before the queue forms, not after.
This sector is not slowing down. The organizations that read these signals as operational directives — not background news — will own the next cycle.
Sources: The Air Current · Defence Industry Europe · L3Harris Technologies · RTX Investor Relations · GuruFocus Defense Coverage

