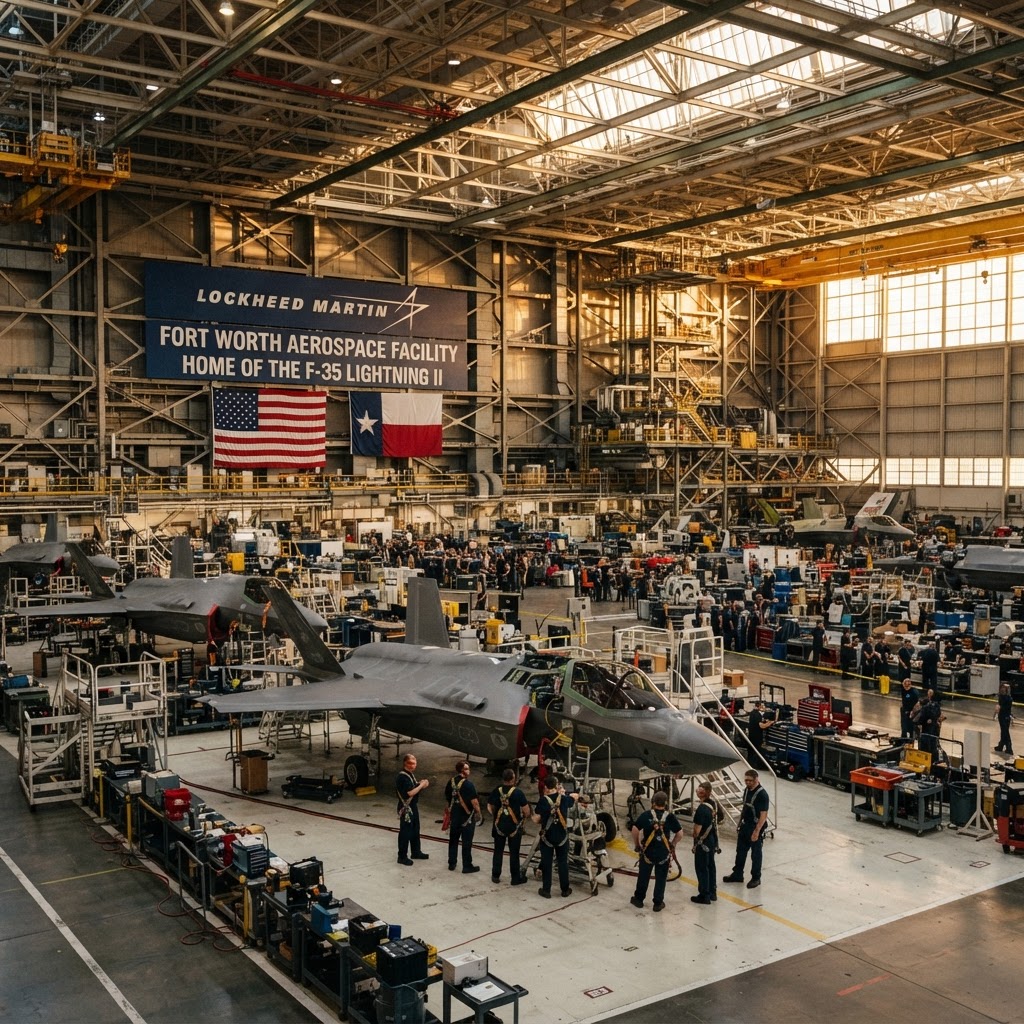

Defense Consolidation, Aerospace Expansion, and Strict New Domestic Manufacturing Mandates: What Manufacturing Leaders Need to Know This Week
By Marcus D. Holloway, Editor in Chief, Strata Intelligence | July 10, 2026
The aerospace and defense manufacturing sector just absorbed four seismic signals in a single week — and taken together, they redraw the competitive map for every supplier, plant operator, and procurement director operating in this space. This is not a cycle. This is a structural reset.
Executive Summary
Between July 6 and July 9, 2026, four distinct but interconnected developments reshaped the strategic priorities of the U.S. aerospace and defense industrial base:
- Lockheed Martin confirmed a $3.45 billion acquisition of naval defense specialist Ultra Maritime, consolidating anti-submarine warfare supply chains.
- SpaceX secured FCC authorization for a 100,000-satellite third-generation Starlink constellation, triggering an unprecedented manufacturing demand wave.
- Boeing moved toward finalizing a 10-aircraft 787 Dreamliner order from Etihad Airways, injecting critical backlog stability into its commercial division.
- The U.S. administration issued a directive mandating major defense contractors build new domestic facilities within two years or face tariff consequences.
Each story operates independently. Together, they represent a coordinated pressure system on manufacturing capacity, capital allocation, and supplier strategy that will define the next 18 to 36 months.
Lockheed Martin's Ultra Maritime Acquisition Reshapes Naval Defense Supply Chains
Lockheed Martin confirmed an agreement to acquire Ultra Maritime from private equity firm Advent International for $3.45 billion, cementing the deal as one of the most consequential naval defense transactions of the decade. Read more
Ultra Maritime is not a peripheral asset. The company is a specialized provider of sonar systems, acoustic intelligence technologies, and anti-submarine warfare platforms — capabilities that sit at the intersection of undersea dominance and great-power competition with China and Russia. Lockheed's decision to absorb it vertically is a calculated move to own more of the kill chain in maritime defense.
Immediate implications for manufacturers and suppliers:
- Tier 2 and Tier 3 acoustic sensor suppliers currently contracting with Ultra Maritime should anticipate a contract review cycle as Lockheed rationalizes the acquired supply base.
- Suppliers who align with Lockheed's existing quality standards — AS9100 certification, ITAR compliance, and MIL-SPEC documentation protocols — will be positioned for continuity. Those who do not will face displacement.
- The acquisition expands Lockheed's manufacturing footprint in the UK and Canada, where Ultra Maritime maintains significant operations, creating cross-border supplier dynamics that procurement teams must factor into sourcing strategies.
Downstream implications:
The consolidation of anti-submarine warfare supply chains under a single prime contractor accelerates a broader trend: the reduction of independent niche players in maritime defense. Plant operators in the sonar, hydrophone, and signal processing subsectors should not wait for contract notices to evaluate their competitive positioning. The window to secure preferred supplier status inside Lockheed's expanded ecosystem is narrow and closing.
"The consolidation of anti-submarine warfare supply chains under a single prime contractor is not a market signal — it is a mandate to act."
The FCC's Starlink Decision Will Generate a Manufacturing Demand Wave Unlike Anything the Sector Has Seen
On July 9, the Federal Communications Commission approved SpaceX's proposal to deploy its third-generation Starlink low-earth orbit constellation — authorizing up to 100,000 satellites. Read more
To place this in industrial context: the existing Starlink network consists of approximately 6,000 satellites. The FCC authorization expands the authorized fleet by a factor of nearly 17. No constellation program in history has demanded this scale of production throughput from the aerospace supply chain.
What this means for the manufacturing sector — in order of urgency:
- Satellite bus and chassis manufacturers face immediate pressure to scale production lines. SpaceX has aggressively pursued vertical integration at its Starbase facility in Texas, but the sheer volume will require external supplier engagement.
- Phased array antenna manufacturers and RF component suppliers will see demand spikes for ground terminal hardware as the expanded constellation requires a proportionally larger user terminal base globally.
- Precision machining and composite fabrication shops that support satellite structural components should begin capacity planning now — not at contract award.
- Launch infrastructure suppliers — including ground support equipment, payload integration systems, and propellant logistics — face a sustained, multi-year demand surge tied to the cadence of Falcon 9 and Starship launch campaigns required to build out the constellation.

What will it take to turn demand into delivered output?
Explore The Capacity Imperative, our report on U.S. advanced manufacturing and the priorities shaping 2027.
The regulatory approval is the starting gun. SpaceX moves faster than any program office in the sector. Suppliers who are not already in commercial conversation with SpaceX's procurement teams should treat this week as a deadline, not a data point.
Boeing's Etihad Order Delivers Backlog Stability — But Production Execution Remains the Real Test
Market sources reported this week that Abu Dhabi-based carrier Etihad Airways is finalizing an agreement to purchase 10 Boeing 787 Dreamliner aircraft. Read more
For Boeing, this order is strategically significant for reasons that extend beyond the revenue line. The company has navigated a sustained period of production quality scrutiny, regulatory oversight from the Federal Aviation Administration, and supply chain disruption. A widebody order of this character from a Gulf carrier signals that commercial market confidence in the 787 program has not collapsed — it has stabilized.
Immediate implications for manufacturers and suppliers:
- Suppliers supporting the 787 program — including those delivering composite fuselage sections, GEnx and Rolls-Royce Trent 1000 engine components, and interior systems — should expect incremental production rate signals from Boeing's Everett and North Charleston facilities.
- The order provides procurement directors within the 787 supply chain a firmer demand horizon for inventory planning and capital investment decisions.
- Boeing's sustained pressure to improve production quality means that supplier nonconformance rates will remain under intense scrutiny. Suppliers who cannot demonstrate disciplined quality management systems risk removal from the program regardless of order volume.
The harder truth: A 10-aircraft order stabilizes sentiment, but it does not resolve Boeing's structural production challenges. The Etihad agreement buys time and goodwill. The test is whether Boeing can convert backlog into deliveries at pace. For suppliers, this distinction matters: backlog is a promise, not a purchase order. Align your production planning to Boeing's actual delivery schedule, not its order book.
The Domestic Manufacturing Mandate Is a Two-Year Clock Every Defense Supplier Must Respect
The most operationally urgent development of the week is one that has received insufficient attention in mainstream coverage. The U.S. administration issued a directive requiring major defense contractors — including Raytheon Technologies — to construct new domestic manufacturing facilities within a two-year timeframe. Contractors who fail to comply face tariff consequences. Read more
This is not guidance. It is not a preference. It is a policy mandate with a hard deadline and a financial penalty mechanism.
The structural implications for the defense industrial base are immediate and layered:
- Capital expenditure reallocation is non-negotiable. Major primes including Raytheon will redirect capital from other priorities to fund domestic facility construction. This compresses discretionary investment in R&D and international expansion.
- Tier 1 suppliers will face demand for domestic production commitments. Prime contractors cannot build domestic facilities and simultaneously source critical components from offshore suppliers without regulatory exposure. Expect domestic sourcing requirements to cascade down the supply chain within 12 months.
- Industrial real estate and skilled labor markets will tighten. Defense-adjacent manufacturing regions — including the I-35 corridor in Texas, the defense manufacturing clusters in Connecticut and Alabama, and aerospace-heavy districts in Arizona — will see increased competition for factory-ready facilities, certified skilled trades, and engineering talent.
- Compliance documentation will become a competitive differentiator. Suppliers who can demonstrate domestic production capacity, ITAR compliance, and workforce investment will gain access to prime contractor relationships that were previously out of reach. Those who cannot will be systematically excluded.
The two-year window is aggressive by any measure of industrial construction timelines. Groundbreaking-to-operational timelines for defense manufacturing facilities routinely run 24 to 36 months under normal permitting and construction conditions. The administration has created a structural tension that will require both accelerated permitting processes and creative facility strategies — including the conversion of existing commercial manufacturing assets — to resolve.
Plant operators and procurement directors who treat this mandate as a future problem are already behind.
Editor's Take: Marcus D. Holloway's 90-Day Outlook
The four developments chronicled this week do not exist in isolation. They form a coherent industrial policy and market signal: the United States is aggressively reshoring, consolidating, and expanding its aerospace and defense manufacturing base simultaneously — and the window for suppliers and plant operators to position themselves within this new architecture is measured in quarters, not years.
Here is what I expect over the next 90 days:
On Lockheed and Ultra Maritime: Integration planning will accelerate immediately. Expect supplier rationalization notices to begin arriving by Q4 2026. Niche maritime acoustics suppliers who are not already inside Lockheed's approved vendor list should initiate qualification conversations now.
On SpaceX Starlink Gen 3: The first procurement signals from SpaceX for constellation-scale component sourcing will emerge before year-end. Suppliers with existing SpaceX relationships are at significant advantage. Those without should pursue commercial outreach through SpaceX's supplier portal without delay.
On Boeing and Etihad: Watch Boeing's monthly delivery data as the leading indicator. If deliveries accelerate through Q3, the production system is stabilizing and supplier demand will firm. If delivery rates stagnate despite the order, it signals continued execution risk and suppliers should avoid over-committing capacity.
On the Domestic Manufacturing Mandate: The 90-day window is the critical planning phase. Raytheon and other affected primes will announce facility investment commitments publicly — likely before year-end — to demonstrate regulatory compliance. Those announcements will carry with them implicit supply chain geography signals. Watch where the facilities are announced. That is where the supplier opportunity concentrates.
The aerospace and defense manufacturing sector is entering a period of forced structural transformation at a pace that leadership teams are not accustomed to managing. The organizations that move with the policy current — rather than waiting to see how it settles — will capture the decade's most significant industrial expansion. The others will be rationalized out of it.
Sources: Lockheed Martin Investor Relations · Federal Communications Commission · Boeing Commercial Airplanes · Raytheon Technologies · SpaceX

