Single-Source Dependency: The Supply Chain Risk Nobody Wants to Talk About
Your plant runs clean. Throughput is up. Your single supplier delivers on time, every time - and has for years. That consistency is exactly why you're exposed.
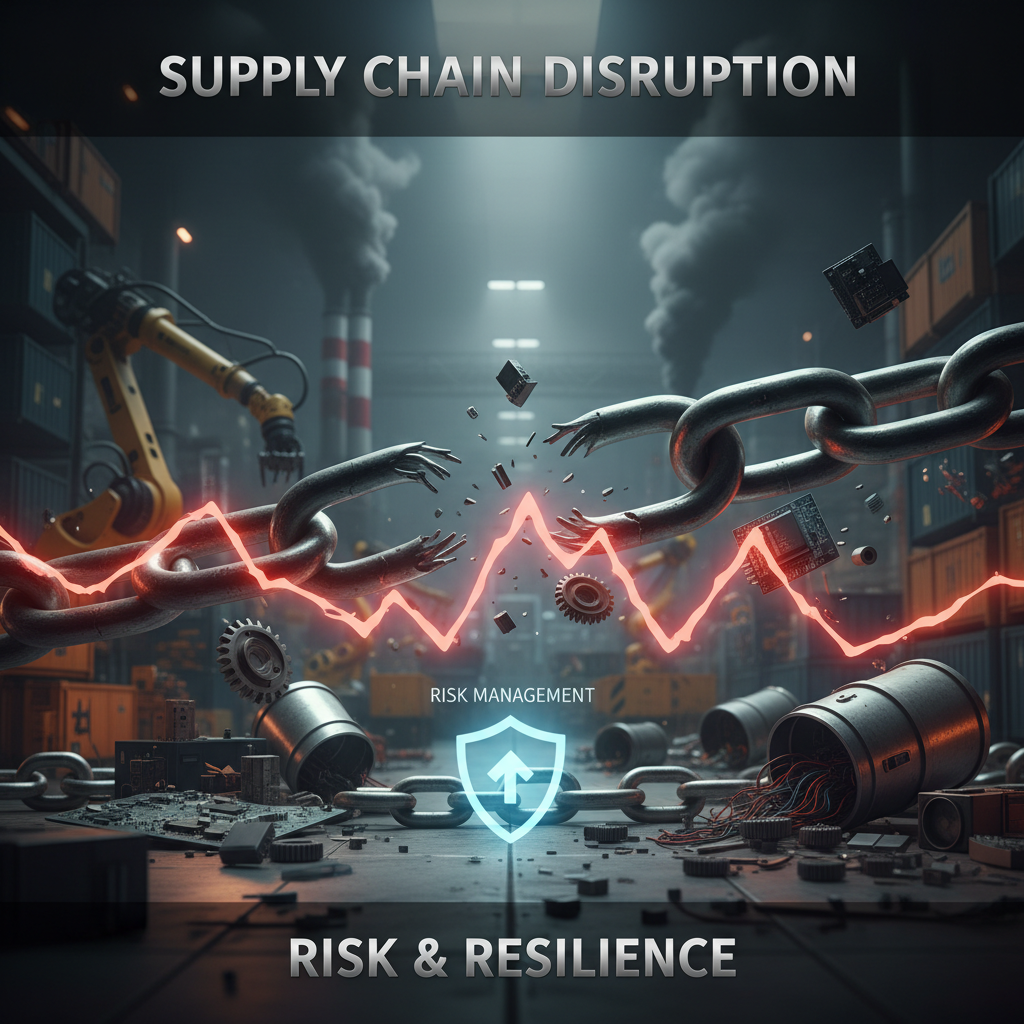
Single-source dependency is the supply chain equivalent of a structural crack hidden behind fresh paint. It doesn't announce itself. It accumulates quietly through procurement decisions that prioritized unit cost over resilience, through relationships that calcified into exclusivity, through operational comfort mistaken for strategic strength. When it breaks, it breaks fast - and the consequences land directly on production schedules, customer commitments, and margin.
The aerospace and automotive sectors learned this the hard way. The chip shortage that began unwinding in 2020 didn't just slow Tesla and Ford - it exposed how deeply single-source logic had penetrated Tier 1 and Tier 2 supply structures across American manufacturing. Companies that had spent years squeezing supplier counts down in the name of lean procurement suddenly found themselves with no leverage, no alternatives, and no runway.
Why Operations Teams Keep Making This Mistake
The incentives are misaligned. Procurement gets rewarded for cost reduction. Consolidating to one supplier almost always delivers better unit pricing, simpler logistics, and stronger volume discounts. Those wins show up on scorecards immediately. The risk they create shows up in a crisis - which is someone else's problem, at someone else's time horizon.
Plant managers compound the issue. Once a single-source relationship matures, switching costs rise sharply: qualified tooling, proprietary specs, embedded process knowledge, NDA-bound documentation. The longer you stay, the harder it is to leave. What started as a vendor selection becomes an operational dependency.
Add geographic concentration to the equation and you have compounding fragility. Many American manufacturers source specialty components - castings, electronics, precision subassemblies - from facilities clustered in specific regions of Asia or Eastern Europe. A single geopolitical event, port disruption, or natural disaster can simultaneously eliminate your supplier and your backup options.
What Resilient Operations Actually Look Like
The manufacturers weathering supply disruptions with minimal production impact share a few structural characteristics:
- Qualified alternates on the shelf. Not theoretical alternatives - actually qualified, tooled, and periodically ordered from. Even a 5–10% volume split with a secondary supplier keeps that relationship active and the qualification current.
- Visible supply tiers. Most vulnerability sits at Tier 2 and Tier 3, not Tier 1. Companies like Toyota and Lockheed Martin have invested in mapping sub-tier supplier networks precisely because single-source risk hides there.
- Contractual protections with teeth. Inventory buffer requirements, advance notice clauses for capacity changes, audit rights. These aren't just legal formalities - they're operational tools.
- Geographic diversification as policy. The CHIPS and Science Act and the broader reshoring push aren't just political narratives. They reflect a structural recalibration happening in boardrooms. Domestic sourcing for critical inputs is increasingly a risk management decision, not just an economic one.

What will it take to turn demand into delivered output?
Explore The Capacity Imperative, our report on U.S. advanced manufacturing and the priorities shaping 2027.
The Audit You're Probably Not Running
Here's a direct question for every operations director reading this: When did you last conduct a single-source dependency audit across your full component list?
Not a theoretical review. A working document that identifies every SKU with one active qualified supplier, maps that supplier's geographic and financial exposure, and assigns a risk tier. Most plants have never done this. Of those that have, most haven't updated the document since the last crisis passed.
The APICS framework and the more recent Supply Chain Operations Reference model both build supplier risk assessment into mature supply chain practice. The tools exist. The discipline is what's missing.
Boeing's production challenges with the 737 MAX - tied in part to complex supplier dependencies and subcontractor quality visibility - illustrate what happens when single-source logic meets manufacturing scale. The costs aren't just financial. They're reputational, regulatory, and operational in ways that take years to reverse.
The Conversation Procurement Won't Start
Single-source dependency persists because no one in the organization has a clear mandate to eliminate it. Procurement owns the supplier relationship. Operations owns throughput. Finance owns cost. Resilience - actual, stress-tested resilience - belongs to nobody until it belongs to everybody in the worst possible moment.
The operations executives who are building durable manufacturing businesses right now are the ones who have made supplier diversification a standing agenda item, not a post-mortem action. They've accepted marginally higher unit costs in exchange for the ability to keep their lines running when the supplier who's been perfect for seven years suddenly isn't.
Comfort is not a strategy. Your cleanest risk is the one you stopped questioning.

